
 By Vincent Howard, CPA | Managing Partner, Howard, Howard and Hodges | SkillAbility for Accounting Firms
Last updated: September 3, 2026 | 36-minute read
- What ASC 250 training should produce
- What is current in ASC 250 in 2026
- Where ASC 250 judgment concentrates
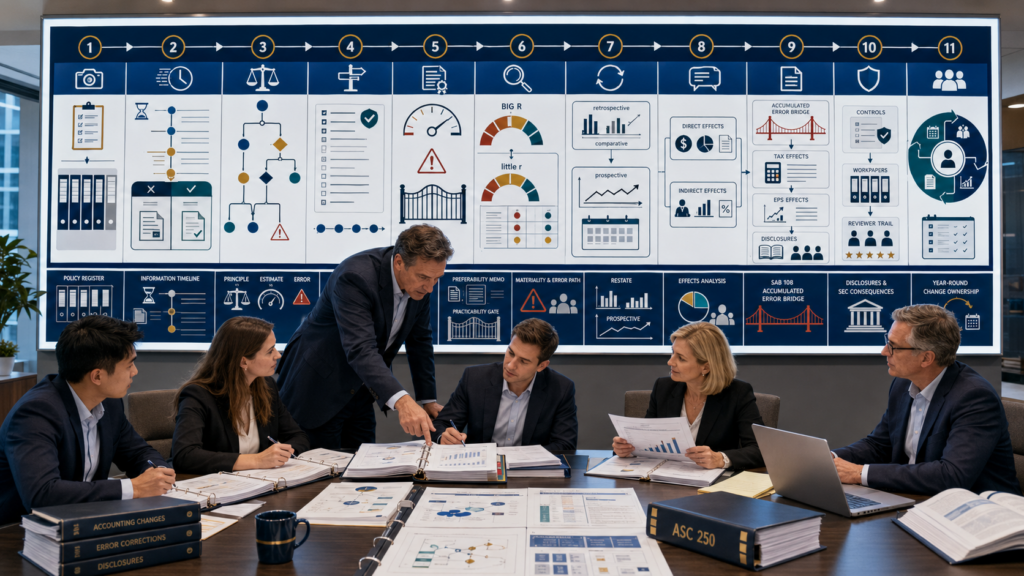
- The CHANGE READY framework
- The four classification lanes
- Changes in accounting principle
- Preferability and voluntary changes
- Retrospective application and impracticability
- Changes in accounting estimate
- Estimate effected by a change in principle
- What is an accounting error?
- Materiality: quantitative + qualitative
- Big R, little r, and out-of-period corrections
- SAB 108: rollover and iron curtain
- Changes in reporting entity
- Worked principle-change example
- Worked estimate-change example
- Worked prior-period error example
- Interim-period considerations
- Quarter-end / year-end ASC 250 workflow
- Self-review checklist
- 100-point ASC 250 readiness scorecard
- 30/60/90-day development plan
- 15 realistic staff scenarios
- What CPA firms should measure
- Frequently asked questions
What Is Accounting Changes and Error Corrections Training?
Accounting changes and error corrections training develops a staff accountant’s ability to classify why previously used accounting changed and then apply the correct retrospective, prospective, or restatement model under ASC 250.
ASC 250 covers:
Change in Accounting Principle
Changing from one acceptable accounting principle or method to another. Voluntary changes generally require preferability and retrospective application.
Change in Accounting Estimate
New information changes the carrying amount or subsequent accounting for existing or future assets and liabilities. Account prospectively.
Change in Reporting Entity
A change in the specific entities comprising the reporting entity can require retrospective presentation.
Correction of an Error
A mathematical mistake, GAAP application mistake, or oversight/misuse of facts existing when the statements were prepared. Material errors are restated.
KPMG’s current October 2025 ASC 250 handbook describes Topic 250 as a “companion standard to all others” because ASC 250 does not choose the underlying accounting principle or estimate—it governs what happens when those principles, methods, estimates, or prior applications change.
That makes this guide a natural bridge to Fixed Asset Accounting Training, CECL Training for Accountants, Revenue Recognition Training, Income Tax Provision Training, and Workpaper Review Checklist.
Why ASC 250 Is a Staff-Judgment Topic
I have practiced public accounting since 1990, founded my accounting firm in 1993, and helped grow Howard, Howard and Hodges from three people to approximately 50 staff. Since 2020, I have built SkillAbility around a recurring development problem: staff often see a number change and assume it is “just an estimate update.”
But that conclusion can change:
- whether prior periods are recast,
- whether retained earnings is adjusted,
- whether previously issued statements are restated,
- whether a public company needs an Item 4.02 Form 8-K,
- whether an auditor preferability letter is needed,
- whether incentive compensation clawback analysis is triggered,
- whether control deficiencies need to be evaluated.
The technical skill is therefore not “know ASC 250 terminology.”
It is:
What Is Current in ASC 250 in 2026?
KPMG’s October 2025 Accounting Changes and Error Corrections Handbook is the current edition in 2026. It applies to all entities and includes updated interpretations on accounting changes, errors, interim periods, and SEC registrants.
| Current 2026 Point | Training Implication |
|---|---|
| ASC 250 model remains stable | Teach the classification and transition model—not a fictional “2026 ASC 250 rewrite.” |
| KPMG October 2025 handbook is current | Current guidance emphasizes classification, materiality, error correction, interim reporting, and SEC-specific considerations. |
| SEC materiality remains qualitative + quantitative | SAB 99 rejects using a percentage threshold as a substitute for full materiality analysis. |
| SAB 108 remains important for registrants | Public companies evaluate accumulated errors using both current-period income-statement and ending-balance-sheet perspectives. |
| Big R and little r remain operationally important | Both are restatements under U.S. GAAP; public-company filing, cover-page, clawback, and governance consequences can differ. |
| ASU 2023-06 remains pending | Its additional change-in-reporting-entity disclosure amendments are not yet effective and could be removed if the SEC has not removed corresponding rules by June 30, 2027. |
| PCAOB estimate focus remains relevant | PCAOB staff continues to identify audit deficiencies around significant assumptions, reinforcing why staff must document new information supporting estimate changes. |
Chart: Where ASC 250 Judgment Concentrates
SkillAbility training heat map—not a FASB or PCAOB ranking. Actual risk depends on materiality, reporting status, estimate uncertainty, comparative periods, interim reporting, internal controls, and whether the issue affects filings already issued.
The CHANGE READY Framework
| Stage | Staff Question | Review Evidence |
|---|---|---|
| C — Capture what changed | What policy, method, assumption, entity boundary, number, presentation, or disclosure changed? | Change intake form |
| H — Hunt for the information timeline | What facts were available when prior statements were prepared, and what information is genuinely new? | Evidence chronology |
| A — Assign the ASC 250 classification | Principle, estimate, estimate effected by principle, reporting entity, or error? | Classification memo |
| N — Navigate transition guidance | Does a new ASU provide a specific transition method? | ASU transition matrix |
| G — Gauge preferability & practicability | Is a voluntary principle change preferable, and can it be applied retrospectively? | Preferability / impracticability memo |
| E — Evaluate materiality & error path | If this is an error, is it material to prior periods, current period, or both? | Materiality analysis |
| R — Recast, restate, or record prospectively | Which periods and balances actually change? | Comparative adjustment schedule |
| E — Explain direct & indirect effects | What changes in retained earnings, EPS, tax, compensation, covenants, or other balances? | Impact bridge |
| A — Assemble disclosures & SEC consequences | What disclosures, filings, preferability letters, checkboxes, or restatement communications are required? | Disclosure / filing checklist |
| D — Document controls & reviewer trail | Can a reviewer reproduce why this is retrospective, prospective, or a restatement? | Final ASC 250 package |
| Y — Year-round change ownership | Are new ASUs, policy decisions, estimate methodology changes, and identified errors captured before filing deadlines? | Quarterly change register |
The Four ASC 250 Classification Lanes
The fastest way to make ASC 250 teachable is to force every issue into one of four primary lanes before calculating anything.
| Classification | What Changed? | Typical Accounting |
|---|---|---|
| Accounting principle | One acceptable GAAP principle/method replaced by another | Retrospective unless transition guidance or impracticability says otherwise |
| Accounting estimate | New information changes expected benefits, obligations, or carrying amounts | Prospective in current and future periods |
| Reporting entity | The specific entities comprising the reporting entity change | Retrospective presentation |
| Error correction | Prior GAAP was misapplied, math was wrong, or existing facts were overlooked/misused | Restatement if material; other correction paths if immaterial |
One critical fifth concept
ASC 250 also recognizes a change in accounting estimate effected by a change in accounting principle.
The classic example is changing depreciation, amortization, or depletion method because management’s estimate of the pattern of consumption changed.
That hybrid classification matters because:
- it is accounted for prospectively like an estimate,
- but the new accounting principle still generally needs to be justified as preferable.
Changes in Accounting Principle: When Retrospective Application Is the Default
A change in accounting principle occurs when an entity changes:
- from one generally accepted accounting principle to another generally accepted accounting principle when more than one is permitted,
- from an accounting principle that is no longer acceptable to one that is acceptable, or
- the method of applying an accounting principle.
New ASU adoption
When a newly issued Accounting Standards Update requires or permits a change, staff should first read the transition provisions of that ASU.
The ASU may require:
- full retrospective application,
- modified retrospective application,
- prospective application,
- another transition method.
ASC 250 does not override those specific transition provisions.
Voluntary principle change
If management voluntarily changes from one acceptable principle or method to another:
- the new method must be preferable,
- the change is generally applied retrospectively unless impracticable,
- comparative financial statements are recast as though the new principle had always been used,
- opening equity of the earliest period presented is adjusted for the cumulative effect relating to periods before those presented.
Examples that can be principle changes
- Changing inventory cost method from FIFO to weighted average when both are acceptable.
- Changing a cost-flow or accounting method used to apply a GAAP principle.
- Changing from an unacceptable principle to GAAP—although that last case is not a voluntary change; it is an error correction.
Preferability: Why Management Cannot Change Accounting Methods for Convenience
A voluntary accounting principle change is allowed only when the new principle is justifiable as preferable.
Preferability is not:
- lower implementation cost,
- higher current-year earnings,
- easier covenant compliance,
- a competitor’s choice by itself,
- management preference without financial-reporting rationale.
Preferability asks whether the change improves financial reporting
Evidence can include:
- better representation of transaction economics,
- improved comparability,
- better matching with how assets or obligations are consumed,
- changed business model or facts making another method more relevant,
- explicit FASB preference for one acceptable method.
SEC registrants
For certain voluntary changes in accounting principle or method, an SEC registrant may need a preferability letter from its independent accountant.
KPMG’s October 2025 handbook notes that among the various accounting changes, the SEC preferability-letter requirement applies to voluntary changes in accounting principle/method.
Changing back later
If management previously concluded Method B was preferable to Method A, it cannot casually revert to Method A because circumstances become inconvenient.
A new change requires a new preferability analysis based on current facts.
Retrospective Application and the Impracticability Exception
Retrospective application is designed to improve comparability.
The comparative periods should look as though the newly adopted accounting principle had been used in those periods.
Typical retrospective mechanics
Direct effects
Direct effects are adjustments necessary to apply the new accounting principle.
Examples:
- inventory balances,
- cost of goods sold,
- deferred taxes directly resulting from the change,
- retained earnings.
Indirect effects
Indirect effects can arise from changes in:
- profit-sharing,
- bonus compensation,
- royalties,
- other contractual amounts calculated from reported financial results.
Those effects can have different recognition timing and require careful review rather than simply being forced into the retrospective schedule.
Impracticability is a high bar
If retrospective application is impracticable, ASC 250 generally requires applying the new principle as of the earliest date practicable.
Impracticability is not the same as:
- “it will take a lot of work,”
- “the old ERP is inconvenient,”
- “we would need to rebuild schedules.”
Staff should document why the required information cannot be reconstructed without:
- unsupported assumptions about management intent in prior periods,
- significant estimates that cannot be objectively distinguished from hindsight,
- other conditions meeting ASC 250’s impracticability criteria.
Changes in Accounting Estimate: New Information, Prospective Accounting
ASC 250 describes a change in accounting estimate as a change that adjusts the carrying amount of an existing asset or liability—or alters subsequent accounting for existing or future assets or liabilities—because of new information.
Examples include:
- allowance for uncollectible receivables,
- inventory obsolescence,
- useful lives of depreciable assets,
- salvage values,
- warranty obligations.
Why estimates change
Estimates are not errors merely because actual results differ.
Estimates are based on information available at a point in time.
New information may come from:
- updated customer credit behavior,
- new claims experience,
- changed operating plans,
- new technological obsolescence evidence,
- updated market data,
- revised expected asset use.
Prospective accounting
Prior periods are not revised merely because a later estimate is better.
The documentation question
Staff should be able to answer:
What new information became available that was not known—or reasonably knowable—when the previous estimate was made?
If the answer is weak, the issue may be an error rather than an estimate change.
This is particularly relevant in CECL, impairments, warranties, contingencies, fair value, and useful-life accounting. See CECL Training for Accountants, Asset Impairment Training, and Contingency Accounting Training.
Change in Estimate Effected by a Change in Principle
This is one of the best ASC 250 staff-training scenarios because the classification sounds contradictory.
The standard recognizes that sometimes:
- a method changes,
- but the method change is inseparable from new information about an estimate.
Classic example: depreciation method
A company uses straight-line depreciation because it originally expects economic benefits to be consumed evenly.
New operating data demonstrates that a machine’s output and maintenance pattern now front-loads economic consumption.
Management changes to an accelerated method that better reflects the consumption pattern.
ASC 250 treats this as a:
Accounting:
- prospective, like an estimate,
- preferability assessment required, because the accounting principle/method changed.
Why this matters
A staff accountant who sees “depreciation method changed” and immediately recasts prior years can materially misstate the financial statements.
What Is an Error in Previously Issued Financial Statements?
ASC 250 defines an error broadly enough to capture more than arithmetic mistakes.
An error can result from:
- mathematical mistakes,
- mistakes in applying GAAP,
- oversight of facts that existed when the statements were prepared,
- misuse of facts that existed when the statements were prepared,
- incorrect recognition, measurement, presentation, or disclosure.
A change from an accounting principle that is not generally accepted to one that is GAAP is also an error correction, not a voluntary principle change.
Error vs estimate: the information timeline controls
Assume a company estimates a 2% warranty rate at December 31.
Six months later, a newly discovered manufacturing defect increases claims.
That can support a new estimate.
Now change the facts.
The manufacturing defect was documented in internal quality reports before December 31, but accounting did not consider those reports.
That looks much more like:
rather than:
Errors can be disclosure-only
A prior-period error is not limited to debit-and-credit mistakes.
Examples include:
- missing required disclosure,
- inaccurate maturity information,
- incorrect classification,
- wrong segment disclosure,
- misstated related-party description,
- incorrect fair-value hierarchy disclosure.
Materiality: Quantitative + Qualitative, Not a 5% Rule
Materiality is the central decision point in error correction.
KPMG’s current ASC 250 handbook says there is no one-size-fits-all rule of thumb for materiality and recommends that all entities consider the SEC staff’s materiality framework.
SAB 99
SEC Staff Accounting Bulletin No. 99 rejects exclusive reliance on numerical thresholds.
A quantitatively small error can be material if it:
- changes a loss into income or vice versa,
- changes an earnings trend,
- causes a target or analyst expectation to be met,
- changes a key performance metric,
- affects compliance with contracts or regulatory requirements,
- affects management compensation,
- conceals an unlawful transaction,
- has other significance to a reasonable investor.
Materiality applies to disclosures too
A missing or inaccurate disclosure can be material even when the underlying account balance is correct.
Assess errors individually and in the aggregate
Staff should not evaluate each error in isolation and stop.
The materiality analysis should consider:
- each error individually,
- aggregate errors,
- specific financial-statement captions,
- related disclosures,
- financial statements as a whole.
Big R, Little r, and Out-of-Period Corrections
For SEC registrants, the practical error-correction framework is often described using three paths.
Big R — reissuance restatement
If an error is material to previously issued financial statements:
- the prior statements should no longer be relied upon,
- the error is corrected by restating and reissuing the affected prior-period financial statements,
- public-company SEC filing consequences can include an Item 4.02 Form 8-K and amended/reissued financial statements, depending on facts.
Little r — revision restatement
If an error is not material to the previously issued financial statements but:
- correcting it in the current period would materially misstate the current period, or
- leaving it uncorrected would materially misstate the current period,
the entity corrects the prior-period information the next time it is presented.
The SEC commonly refers to this as a little r or revision restatement.
Immaterial to prior and current periods
If the error is immaterial to previously issued financial statements and correcting it in the current period is also immaterial, correction can generally be recorded as an out-of-period adjustment in the current period.
Staff should still document:
- error nature,
- period of origin,
- quantitative effect,
- qualitative factors,
- aggregation with other errors,
- current-period correction.
Both Big R and little r are error restatements
SEC guidance emphasizes that both paths correct errors in previously issued financial statements.
The difference is primarily:
- materiality to prior statements,
- reliance status,
- filing/reporting process,
- timing of correction.
Public-company clawback implications
Listed-company clawback policies implementing Exchange Act Rule 10D-1 generally encompass both Big R and little r accounting restatements.
That means the staff’s initial ASC 250 classification can eventually affect:
- governance,
- executive compensation recovery,
- annual-report checkboxes,
- filing disclosures.
SAB 108: Rollover and Iron-Curtain Views of Accumulated Errors
SEC Staff Accounting Bulletin No. 108 addresses a common problem: small errors can accumulate on the balance sheet over several years.
Rollover approach
The rollover approach focuses on the amount by which the current-period income statement is misstated.
Iron-curtain approach
The iron-curtain approach focuses on the amount by which the ending balance sheet is misstated, regardless of when the error originated.
Why both matter
Example:
A company overaccrues an expense by $30,000 per year for five years.
At Year 5:
- current-year P&L error = $30,000,
- cumulative balance-sheet liability overstatement = $150,000.
Looking only at the $30,000 current-year amount can hide the significance of the accumulated $150,000 balance-sheet error.
For public-company training, staff should understand both perspectives even when the final materiality conclusion requires broader qualitative analysis under SAB 99.
Changes in Reporting Entity
ASC 250 also addresses changes in the reporting entity.
These changes can arise when the specific entities that make up the reporting entity change in a way that requires comparative presentation as though the new entity composition had existed in prior periods.
Examples can include
- changing from separate-company statements to consolidated statements when the entities were under common control in the periods presented, depending on the applicable consolidation/common-control guidance,
- changes in the specific subsidiaries or business units comprising combined financial statements,
- other changes that alter the reporting entity rather than merely reflecting a purchase or disposal accounted for under another Topic.
Accounting
Changes in reporting entity are generally reflected retrospectively in comparative financial statements.
The disclosure should explain:
- nature of the change,
- reason for the change,
- effects on income from continuing operations, net income, and related per-share amounts where applicable.
2026 pending disclosure note
ASU 2023-06 contains pending amendments that would expand certain disclosure requirements for changes in reporting entity.
As of September 2026, the KPMG handbook states those provisions are not yet effective and may never become effective if the SEC has not removed the corresponding disclosure requirements from Regulations S-X or S-K by June 30, 2027.
Do not implement the pending Codification language as though it is current GAAP.
Worked Example 1: Voluntary Change in Accounting Principle
A calendar-year private company changes an inventory costing method from Method A to Method B on January 1, Year 4.
Both methods are acceptable under U.S. GAAP, and management concludes Method B is preferable because it better reflects the economics and improves comparability with operations.
Comparative financial statements presented
- Year 4
- Year 3
- Year 2
Recalculated effects
| Period | Inventory Increase | Pretax Income Increase | Tax Effect at 25% |
|---|---|---|---|
| Before Year 2 | $240,000 | Cumulative | $60,000 |
| Year 2 | $40,000 incremental | $40,000 | $10,000 |
| Year 3 | $55,000 incremental | $55,000 | $13,750 |
Opening Year 2 equity adjustment
Then:
- Year 2 is recast under Method B.
- Year 3 is recast under Method B.
- Year 4 uses Method B.
- Comparative disclosures explain the nature, reason, preferability, and financial-statement effects of the change.
What if management cannot recreate Year 2 data?
That does not automatically make retrospective application impracticable.
The team should first evaluate whether:
- source records exist,
- inventory detail can be reconstructed,
- reasonable calculations can be performed without hindsight,
- the ASC 250 impracticability criteria are actually met.
Worked Example 2: Useful-Life Change
A machine originally cost $1,200,000.
At the beginning of Year 4:
- accumulated depreciation = $450,000,
- carrying amount = $750,000,
- original remaining life = 5 years,
- new engineering information indicates only 3 years of remaining service life,
- salvage value remains $0.
This is a change in estimate if the new life results from new information rather than an error in the original estimate.
Do not reopen Years 1–3 simply because today’s estimate is different.
But what if the shorter life was known before Year 3 statements were issued?
If an engineering report available before issuance clearly established the shortened life and accounting ignored it, the issue may be an error.
That is why every estimate-change memo needs an information chronology.
Worked Example 3: Prior-Period Error and Materiality
A company discovers in Year 4 that it failed to accrue a Year 3 contractual bonus.
Facts:
- Year 3 bonus obligation: $420,000
- Year 3 pretax income reported: $6.0M
- Year 4 expected pretax income before correction: $4.5M
- the contract and performance data existed before Year 3 statements were issued,
- accounting simply overlooked the obligation.
Classification
This is not a Year 4 estimate change.
The relevant facts existed when Year 3 financial statements were prepared.
Materiality analysis
The $420,000 is 7% of reported Year 3 pretax income.
But staff should not stop at 7%.
They should also consider:
- whether the error changed an earnings trend,
- whether it affected a bonus threshold,
- whether it affected debt covenants,
- whether other errors aggregate with it,
- whether omission was intentional.
If material to Year 3, the correction is a restatement of Year 3.
If not material to Year 3 but booking the full $420,000 in Year 4 would materially distort Year 4, a little r revision-restatement path may be required for a registrant.
Interim-Period Considerations
ASC 250 also applies to interim financial reporting, but interim periods add another layer of materiality and presentation judgment.
Accounting changes
The broad annual concepts remain:
- material accounting-principle changes are generally reflected retrospectively,
- changes in reporting entity are generally retrospective,
- changes in estimates are generally prospective.
Error corrections
Errors identified during an interim period must be evaluated against:
- the interim period in which the error originated,
- year-to-date information,
- prior annual financial statements,
- current annual-period expectations.
KPMG’s current handbook notes supplemental interim materiality guidance and several specific interim items that can require retrospective adjustment when criteria are met, including certain litigation settlements, income taxes, renegotiation proceedings, and utility revenue items.
Staff development point
Do not assume:
“We’ll fix it in Q4, so the quarterly statements don’t matter.”
Materiality and error correction have to be assessed when each interim financial statement is prepared.
Direct Effects, Indirect Effects, and the Ripple Through the Financial Statements
ASC 250 training should extend beyond the primary account being changed.
Direct effects
Direct effects are amounts necessary to apply the accounting change itself.
Examples:
- inventory,
- cost of goods sold,
- depreciation,
- allowance balances,
- deferred tax effects directly tied to the change.
Indirect effects
Indirect effects arise because other arrangements depend on the changed financial result.
Examples:
- management bonuses,
- profit-sharing plans,
- royalties,
- earnouts,
- debt-covenant calculations,
- performance-based compensation.
Other financial-reporting ripple effects
Staff should also check:
- EPS,
- segment information,
- cash-flow classification,
- income taxes,
- MD&A for registrants,
- critical accounting estimate disclosure,
- debt covenant compliance,
- going concern,
- compensation clawbacks,
- internal control over financial reporting.
A Quarter-End / Year-End ASC 250 Workflow
| Timing | Primary Activities |
|---|---|
| Pre-close | Refresh new-ASU tracker, accounting policy register, estimate-methodology changes, reporting-entity changes, audit adjustments, waived differences, and identified errors. |
| Day 0–1 | Capture each change/error in one intake register; identify underlying GAAP and evidence chronology. |
| Day 1–2 | Classify principle, estimate, estimate effected by principle, reporting entity, or error. Read specific ASU transition provisions first. |
| Day 2–3 | Complete preferability/impracticability analysis for principle changes and quantitative/qualitative materiality analysis for errors. |
| Day 3–4 | Build retrospective recast, prospective estimate schedule, or restatement/revision schedule; calculate tax/EPS and other direct effects. |
| Day 4–5 | Evaluate indirect effects, SEC consequences, controls, covenants, compensation, disclosures, and interim impacts. |
| Final review | Tie comparative statements, opening equity, disclosures, materiality memo, journal entries, filing checklists, and reviewer signoff. |
Build one ASC 250 change-and-error register
Suggested fields:
- Issue ID
- Date identified
- Account / disclosure affected
- Underlying accounting Topic
- Description of what changed
- Information available in prior period
- New information date
- ASC 250 classification
- New ASU transition guidance?
- Preferability required?
- Retrospective application practicable?
- Prior-period effect
- Current-period effect
- Future-period effect
- Quantitative materiality
- Qualitative materiality
- Aggregate misstatement effect
- Big R / little r / out-of-period path
- Tax effect
- EPS effect
- Disclosure effect
- Control deficiency effect
- SEC / filing consequence
- Reviewer
ASC 250 Self-Review Checklist Before Manager Review
- Did I identify exactly what changed?
- Did I identify the underlying accounting Topic?
- Did I determine whether a new ASU contains specific transition requirements?
- Did I avoid applying ASC 250’s generic transition model over an ASU’s specific transition guidance?
- Did I document the date the change or error was identified?
- Did I build a chronology of information available when prior statements were prepared?
- Did I distinguish genuinely new information from information that existed but was overlooked?
- Did I classify the issue as a change in accounting principle, estimate, reporting entity, or error?
- Did I consider whether it is a change in estimate effected by a change in principle?
- Did I identify whether a method change is inseparable from a changed estimate?
- Did I identify whether prior accounting was acceptable GAAP?
- If prior accounting was not GAAP, did I classify the change as an error correction rather than a voluntary principle change?
- For a voluntary principle change, did I document why the new principle is preferable?
- Did I avoid using lower cost or higher earnings as the sole preferability rationale?
- Did I identify whether the FASB explicitly prefers the new method?
- For an SEC registrant, did I assess whether an auditor preferability letter is required?
- Did I determine whether retrospective application is required?
- Did I recalculate all comparative periods presented when practicable?
- Did I calculate the cumulative effect before the earliest period presented?
- Did I adjust opening retained earnings or other equity appropriately?
- Did I identify direct tax effects of the principle change?
- Did I update EPS for affected comparative periods?
- Did I update notes and historical summaries affected by the change?
- Did I evaluate indirect effects such as bonus or profit-sharing changes?
- If retrospective application is claimed impracticable, did I document why?
- Did I distinguish impracticability from inconvenience or cost?
- Did I apply the change as of the earliest practicable date when full retrospective treatment was impracticable?
- For an estimate change, did I identify the new information supporting the revised estimate?
- Did I explain why the prior estimate was reasonable based on information then available?
- Did I apply the estimate change prospectively?
- Did I affect the current period only if that is the only period affected?
- Did I affect current and future periods if both are affected?
- Did I avoid reopening prior periods simply because actual results differ from estimates?
- For a useful-life change, did I recalculate depreciation from the current carrying amount?
- For a salvage-value change, did I apply the revision prospectively?
- For CECL or warranty changes, did I distinguish new portfolio/claims information from previously ignored evidence?
- For a depreciation-method change, did I evaluate change-in-estimate-effected-by-principle guidance?
- Did I account for that hybrid change prospectively?
- Did I complete the required preferability analysis for that hybrid change?
- Did I identify mathematical mistakes?
- Did I identify GAAP application mistakes?
- Did I identify facts that existed but were overlooked?
- Did I identify facts that existed but were misused?
- Did I identify presentation errors?
- Did I identify classification errors?
- Did I identify disclosure errors?
- Did I identify a prior non-GAAP policy corrected to GAAP as an error?
- Did I quantify each error by period?
- Did I quantify the effect on each affected financial-statement caption?
- Did I quantify related disclosure errors?
- Did I evaluate errors individually?
- Did I aggregate all uncorrected and identified errors?
- Did I evaluate both quantitative and qualitative materiality?
- Did I avoid treating 5% or another percentage as an automatic safe harbor?
- Did I evaluate whether the error changes a trend?
- Did I evaluate whether the error changes income to loss or loss to income?
- Did I evaluate whether it affects analyst/management targets?
- Did I evaluate covenant effects?
- Did I evaluate compensation effects?
- Did I evaluate unlawful transaction concealment?
- Did I evaluate management intent where relevant to qualitative materiality?
- Did I evaluate whether the error is material to prior-period statements?
- If material to prior statements, did I identify Big R restatement requirements?
- Did I determine whether prior statements can continue to be relied upon?
- For a registrant, did I evaluate Item 4.02 Form 8-K implications?
- Did I evaluate amended/reissued filing requirements?
- If not material to prior statements, did I evaluate whether current-period correction would be material?
- Did I evaluate whether leaving the error uncorrected would materially misstate the current period?
- Did I identify little r revision-restatement requirements when applicable?
- If immaterial to prior and current periods, did I document the out-of-period adjustment conclusion?
- Did I identify the year(s) in which an accumulated error originated?
- For a registrant, did I evaluate the rollover approach under SAB 108?
- For a registrant, did I evaluate the iron-curtain approach under SAB 108?
- Did I avoid focusing only on the current-year P&L effect when a balance-sheet error accumulated over years?
- Did I evaluate listed-company clawback consequences?
- Did I evaluate annual-report error-correction checkboxes where applicable?
- Did I determine whether there was a change in reporting entity?
- Did I distinguish reporting-entity changes from acquisitions/disposals under another Topic?
- Did I apply a qualifying reporting-entity change retrospectively?
- Did I update reporting-entity disclosures?
- Did I avoid prematurely applying pending ASU 2023-06 requirements?
- Did I evaluate interim-period effects?
- Did I evaluate the error against both interim and year-to-date information?
- Did I evaluate prior annual financial statements?
- Did I identify current-year tax effects?
- Did I identify deferred tax effects?
- Did I identify cash-flow statement effects?
- Did I identify segment effects?
- Did I identify going-concern effects?
- Did I identify debt-classification/covenant effects?
- Did I identify compensation and earnout effects?
- Did I identify internal-control implications?
- Did I evaluate whether the issue indicates a control deficiency?
- Did I evaluate severity of any control deficiency under the applicable framework?
- Did comparative financial statements tie after recast/restatement?
- Did opening retained earnings tie?
- Did disclosure amounts tie to the adjustment schedule?
- Did journal entries tie to the general ledger?
- Can another accountant reproduce why the issue is retrospective, prospective, or a restatement?
- Can another accountant explain the difference between the accounting change and any related error correction?
100-Point ASC 250 Readiness Scorecard
| Capability | Points | Observable Evidence |
|---|---|---|
| Issue capture / evidence chronology | 10 | What changed and when information existed are clearly documented |
| ASC 250 classification | 16 | Principle, estimate, hybrid, entity, and error distinctions are correct |
| Transition / preferability / impracticability | 14 | ASU transition and voluntary-change requirements are supported |
| Retrospective / prospective mechanics | 12 | Comparatives, opening equity, current/future estimates are correct |
| Error materiality | 16 | Quantitative + qualitative, individual + aggregate analysis is complete |
| Big R / little r / SAB 108 | 12 | Correct restatement/correction path and cumulative error analysis |
| Reporting entity / interim issues | 8 | Retrospective entity changes and interim effects handled correctly |
| Direct/indirect effects / disclosures | 6 | Tax, EPS, compensation, notes, and other effects are captured |
| Controls / reviewer trail | 6 | Issue register, ICFR implications, entries, and signoff reconcile |
Suggested readiness bands
- 90–100: Ready to own defined ASC 250 change/error workstreams with normal manager/technical review.
- 82–89: Generally review-ready; targeted coaching remains in materiality, preferability, or SEC consequences.
- 72–81: Controlled ownership with checkpoints before classification and restatement conclusions are finalized.
- Below 72: Continue structured ASC 250 practice.
Override the numerical score for deliberately labeling an error as an estimate to avoid restatement, manipulating materiality thresholds, suppressing cumulative errors, backdating policy changes, fabricating impracticability, or withholding facts that existed when prior statements were prepared.
A 30/60/90-Day ASC 250 Training Plan
| Period | Development Goal | Practice | Evidence |
|---|---|---|---|
| Days 1–30 | Classify change vs error | Principle, estimate, hybrid, entity, error; evidence timelines | Ten clean ASC 250 classification memos |
| Days 31–60 | Own retrospective/prospective mechanics | Preferability, recasts, opening equity, estimate updates, disclosures | Review-ready change package |
| Days 61–90 | Own error materiality and SEC paths | SAB 99, SAB 108, Big R/little r, interim effects, controls | Observed judgment and escalation quality |
Days 1–30: Train classification before calculation
Use scenarios where the same account changes for different reasons:
- depreciation because expected life changed,
- depreciation because the original life ignored existing engineering evidence,
- depreciation method changed because consumption pattern changed,
- inventory method voluntarily changed,
- inventory method corrected because the old method was not GAAP.
Require staff to explain the information timeline before selecting retrospective or prospective accounting.
Days 31–60: Build the comparative schedules
Give staff:
- three years of comparative statements,
- opening equity data,
- tax rates,
- EPS information,
- bonus arrangements,
- debt covenants.
Require them to build a complete principle-change or estimate-change package.
Days 61–90: Add materiality and reporting consequences
Use errors that:
- are quantitatively small but change a loss to income,
- accumulate over several years,
- are immaterial to prior year but material if booked entirely in the current year,
- affect incentive compensation,
- trigger possible control deficiencies.
Use Scenario-Based Training for Accountants so staff practice recognizing when a technical-accounting or SEC reporting escalation is required.
15 Realistic ASC 250 Training Scenarios
1. Useful life shortens because of new operating data
Staff identifies a change in estimate and applies the revision prospectively.
2. Useful life was wrong because accounting ignored an existing engineering report
Staff identifies a prior-period error rather than calling it a new estimate.
3. Depreciation method changes because consumption pattern changes
Staff identifies a change in estimate effected by a change in principle: prospective accounting plus preferability.
4. Inventory costing changes from one acceptable method to another
Staff documents preferability and applies the voluntary principle change retrospectively when practicable.
5. Company adopts a newly effective ASU
Staff reads the ASU’s specific transition provisions instead of defaulting automatically to ASC 250 retrospective application.
6. Prior accounting method was never GAAP
Changing to GAAP is classified as an error correction, not a voluntary principle change.
7. Warranty reserve rises after a new defect emerges
If the defect truly arose or became known through new information, staff applies an estimate change prospectively.
8. Warranty reserve rises after old quality-control reports are discovered
If those reports existed and should have been considered, staff evaluates a prior-period error.
9. Error is 2% of pretax income but flips EPS from a miss to a beat
Staff does not dismiss the error as immaterial merely because it is below a quantitative benchmark.
10. $25K expense error accumulates for six years
A registrant evaluates both rollover and iron-curtain effects instead of looking only at the latest year’s $25K.
11. Prior-year error is immaterial, but booking it now would distort current earnings
Staff identifies the potential little r revision-restatement path.
12. Prior-year material error is found after issuance
Staff escalates a Big R reissuance-restatement analysis and related filing/control consequences.
13. Comparative entity composition changes
Staff evaluates whether the issue is a change in reporting entity requiring retrospective presentation rather than an acquisition/disposal under another Topic.
14. Management says historical data is too hard to rebuild
Staff does not accept inconvenience as impracticability and documents whether ASC 250’s actual threshold is met.
15. Material disclosure was omitted but the numbers were correct
Staff recognizes that ASC 250 errors include presentation and disclosure errors—not only monetary journal-entry errors.
What CPA Firms Should Measure
| Metric | What It Reveals |
|---|---|
| Principle/estimate/error reclassifications by reviewer | Core ASC 250 classification competence |
| Estimate changes without evidence chronology | Risk that errors are being mislabeled as estimates |
| Preferability memos reconstructed by manager | Voluntary policy-change judgment |
| Retrospective schedules corrected | Comparative and opening-equity execution |
| Materiality conclusions changed after review | SAB 99 / qualitative judgment quality |
| Accumulated errors missed | SAB 108 / multi-period awareness |
| Big R/little r path corrections | Restatement and SEC-readiness competence |
| Disclosure/control consequences missed | Whole-financial-reporting awareness |
| Manager reconstruction hours | Whether staff own the evidence chain |
Connect these measures to your Staff Accountant Competency Checklist, Accounting Employee Development Plan, Workpaper Review Checklist, and Accountants Shifting From Preparers to Reviewers.
Common ASC 250 Training Mistakes
Mistake 1: Call every changed number an estimate
The accountant never asks whether the underlying facts existed in the prior period.
Mistake 2: Call every method change a principle change
Depreciation-method changes and other hybrid estimate/principle changes are mishandled.
Mistake 3: Ignore ASU transition language
Staff applies generic retrospective treatment when the new standard provides its own transition method.
Mistake 4: Treat “preferable” as “easier”
Operational convenience is substituted for improved financial reporting.
Mistake 5: Treat expensive retrospective work as impracticable
The high ASC 250 threshold is replaced by a project-budget threshold.
Mistake 6: Use a 5% materiality safe harbor
Qualitative factors, disclosure effects, trends, compensation, and covenants are ignored.
Mistake 7: Look only at the current-year error
Accumulated balance-sheet misstatements are missed.
Mistake 8: Assume “not material to last year” means book everything this year
The team fails to consider whether current-period correction creates a material distortion.
Mistake 9: Correct the journal entry but not the disclosures
EPS, tax, historical summaries, notes, and SEC consequences stay wrong.
Mistake 10: Ignore internal controls
A significant error is corrected without asking why the control system failed to prevent or detect it.
How SkillAbility Builds ASC 250 Capability
BASE — Classification and mechanics
- Principle vs estimate vs error
- evidence chronology
- retrospective vs prospective
- opening-equity adjustments
- estimate schedules
MAPS — Judgment and materiality
- Preferability
- impracticability
- hybrid estimate/principle changes
- SAB 99 qualitative materiality
- SAB 108 accumulated errors
- Big R / little r
SUMMIT — Reviewer and reporting readiness
- Review materiality memos
- review comparative recasts/restatements
- coordinate audit/SEC/legal/tax implications
- evaluate controls and governance
- manage interim and reporting-entity effects
- coach staff without rebuilding the entire issue chronology
Frequently Asked Questions About ASC 250
What is ASC 250?
ASC 250 is the U.S. GAAP Topic governing accounting changes and error corrections, including changes in accounting principle, accounting estimate, reporting entity, and corrections of errors in previously issued financial statements.
What is the difference between a change in accounting principle and a change in estimate?
A principle change replaces one acceptable GAAP principle or method with another. An estimate change results from new information about expected benefits, obligations, or carrying amounts. Principle changes are generally retrospective; estimate changes are prospective.
How are changes in accounting principle accounted for?
A voluntary principle change is generally applied retrospectively to prior periods presented when practicable and is permitted only when the new principle is preferable. Adoption of a new ASU follows the transition provisions specified in that ASU.
How are changes in accounting estimates accounted for?
Changes in accounting estimates are accounted for prospectively in the period of change and future periods when affected.
Is changing depreciation method retrospective or prospective?
A change in depreciation method for long-lived nonfinancial assets is generally treated as a change in estimate effected by a change in accounting principle. It is accounted for prospectively, but the new method generally must be justified as preferable.
What is a prior-period error under ASC 250?
An error includes mathematical mistakes, mistakes in applying GAAP, and oversight or misuse of facts that existed when the financial statements were prepared. Errors can affect recognition, measurement, presentation, or disclosure.
Is changing from non-GAAP accounting to GAAP a change in principle?
No. Changing from an accounting principle that is not generally accepted to one that is accepted is a correction of an error.
What does retrospective application mean?
Retrospective application means recasting comparative financial statements as if the new accounting principle had been used in prior periods, including adjustment of opening equity of the earliest period presented for cumulative effects relating to earlier periods.
What if retrospective application is impracticable?
The change is generally applied as of the earliest date practicable. Impracticability is a high threshold and is not established merely because reconstructing prior information is expensive or inconvenient.
What is preferability under ASC 250?
Preferability means the new accounting principle provides better financial reporting under the entity’s circumstances. A voluntary principle change generally requires support that the new principle is preferable.
What is a Big R restatement?
Big R is common SEC terminology for a reissuance restatement required when an error is material to previously issued financial statements.
What is a little r restatement?
Little r is common SEC terminology for a revision restatement when an error is not material to previously issued statements but correcting it in the current period—or leaving it uncorrected—would materially misstate the current period.
Are Big R and little r both restatements?
Yes. SEC guidance explains that both constitute accounting restatements to correct errors in previously issued financial statements, although the filing and reliance consequences differ.
What is an out-of-period adjustment?
An out-of-period adjustment is generally a current-period correction of an error that is immaterial to both previously issued financial statements and the current-period financial statements after considering the correction.
Does a 5% threshold determine materiality?
No. SAB 99 explains that numerical benchmarks can be an initial analytical step but cannot replace consideration of all quantitative and qualitative facts.
What is SAB 108?
SAB 108 provides SEC staff guidance on quantifying errors by considering both current-period income-statement effects and cumulative ending-balance-sheet effects, commonly associated with rollover and iron-curtain perspectives.
Can a disclosure mistake be an ASC 250 error?
Yes. ASC 250 errors include mistakes in presentation or disclosure as well as recognition and measurement.
What is a change in reporting entity?
A change in reporting entity changes the specific entities whose financial information is presented as the reporting entity. Qualifying changes are generally presented retrospectively.
Does ASC 250 apply to private companies?
Yes. ASC 250 applies to all entities, including public companies, private companies, and not-for-profit entities. SEC registrants have additional SEC-specific requirements.
How do you know when a staff accountant is review-ready for ASC 250?
A review-ready staff accountant can build the information chronology, classify the issue, apply transition guidance, document preferability or estimate evidence, assess error materiality, distinguish Big R/little r paths, calculate comparative effects, and connect the conclusion to disclosures and controls.
Current Research and Authority Resources
- KPMG — Accounting Changes and Error Corrections Handbook, October 2025
- KPMG — Full ASC 250 Handbook PDF, October 2025
- SEC — Staff Accounting Bulletin No. 99: Materiality
- SEC — Staff Accounting Bulletin No. 108
- SEC Office of the Chief Accountant — Assessing Materiality and Error Corrections
- SEC — Exchange Act Forms C&DIs, Error-Correction Annual-Report Checkbox Guidance
- PCAOB — Audit Focus: Auditing Accounting Estimates, May 2025
- Google Search Central — Optimizing for Generative AI Features
- Google Search Console — Generative AI Performance Report
ASC 250 can intersect with virtually every Topic in U.S. GAAP, plus ASC 270 interim reporting, ASC 260 EPS, ASC 740 income taxes, ASC 855 subsequent events, ASC 205 presentation, ASC 275 risks and uncertainties, and SEC/PCAOB requirements. Verify current authoritative literature and entity-specific facts for live work.
The Bottom Line
ASC 250 training should not produce staff who simply know the words “retrospective” and “prospective.”
It should produce accountants who can prove why a changed number belongs in one category or the other.
Start with the information timeline.
Classify principle, estimate, hybrid, reporting entity, or error before calculating.
Follow a new ASU’s transition provisions first.
Require preferability for voluntary principle changes.
Apply principle changes retrospectively when practicable.
Apply estimate changes prospectively.
Do not disguise old facts as new information.
Assess errors quantitatively and qualitatively.
Evaluate accumulated errors, not only the current year’s flow.
Distinguish Big R, little r, and immaterial correction paths.
Trace the effect through tax, EPS, compensation, covenants, disclosures, and controls.
That is CHANGE READY.
Protect Knowledge. Develop People. Scale the Firm.
Can Your Staff Tell an Estimate Change From an Error Before It Becomes a Restatement?
SkillAbility helps accounting firms develop staff who can classify accounting changes, build retrospective and prospective schedules, assess prior-period errors, document materiality, and produce review-ready ASC 250 workpapers.
Book Your Free 10-Minute Structural Alignment Review →
Includes our 45-Day Out-of-Pocket Performance Guarantee.
To staff who can explain why the prior period changes—or why it doesn’t,
Vincent Howard, CPA
Managing Partner, Howard, Howard and Hodges
SkillAbility for Accounting Firms
About the Author
Vincent Howard, CPA has practiced public accounting since 1990. He earned a Bachelor of Science in Accounting and a Master’s in Taxation from the University of Central Florida, founded his accounting firm in 1993, and serves as Managing Partner of Howard, Howard and Hodges. He helped grow the organization from three people to approximately 50 staff across multiple Florida locations and states. He has participated in PASBA since 1997, and the firm was named PASBA Firm of the Year in 2015. Through SkillAbility, he helps accounting firms convert technical knowledge into structured staff development and review-ready work.
How This Guide Was Developed
This guide combines Vincent Howard’s public-accounting and workforce-development experience with KPMG’s October 2025 Accounting Changes and Error Corrections Handbook, SEC Staff Accounting Bulletins 99 and 108, current SEC guidance on Big R and little r restatements, PCAOB accounting-estimate guidance, and SkillAbility’s fixed-asset, CECL, impairment, contingency, tax-provision, scenario-training, workpaper-review, and reviewer-development frameworks. CHANGE READY and the 100-point readiness scorecard are original SkillAbility teaching frameworks designed to turn ASC 250 classification and correction decisions into observable staff judgment.
© 2026 SkillAbility for Accounting Firms. This article provides general educational information and does not replace client-specific U.S. GAAP, audit, tax, legal, SEC, regulatory, valuation, governance, or other professional advice.